
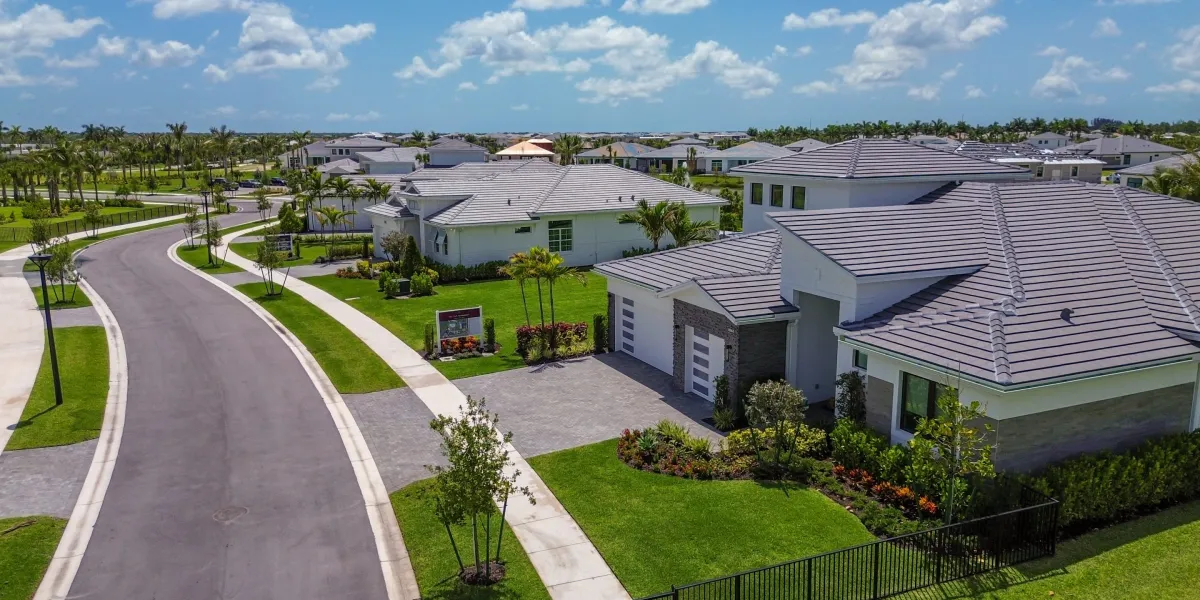
For decades, the American dream has been synonymous with homeownership, viewed as both a sanctuary and a reliable nest egg. However, recent data suggests that treating a primary residence as a primary investment strategy might be a losing game compared to the stock market. While home prices have certainly risen, they have been completely eclipsed by the explosive growth of the S&P 500, which has benefited from a massive AI-driven rally and consistent double-digit gains reminiscent of the late nineties.
The numbers tell a stark story of divergence. Between late 2015 and late 2025, the Case-Shiller Index showed home prices climbing by eighty seven percent, yet during that same window, the S&P 500 surged by two hundred thirty five percent before even accounting for dividends. This gap is becoming particularly apparent to younger generations who find themselves priced out of the housing market due to high entry costs and mortgage rates hovering above seven percent. Rather than scraping together impossible down payments, many are opting to rent and channel their savings into equities, finding that this path builds wealth far more efficiently.
Economists Ray Fisman and Michael Luca argue that society needs to stop bundling the decision of where to live with the decision of how to invest. Buying a home forces someone to lock a huge portion of their life savings into a single, illiquid asset, which contradicts basic financial advice regarding diversification. While leverage can make modest home price increases feel like huge wins on paper, it also creates significant risk if values dip. In contrast, stocks offer liquidity and broader exposure across various industries, making them a more flexible tool for growing capital.
Despite these trends, owning a home still offers emotional security and freedom from landlords that cannot be quantified on a spreadsheet. Interestingly, those who are still determined to buy may find some leverage today as the market cools. Recent reports indicate an increase in seller concessions, ranging from mortgage rate buy downs to lavish perks like free cruises or vacations just to close a deal. Ultimately, while these incentives make entering the market easier, they do little to change the underlying reality that for pure profit, the stock ticker has far outperformed the front porch.