
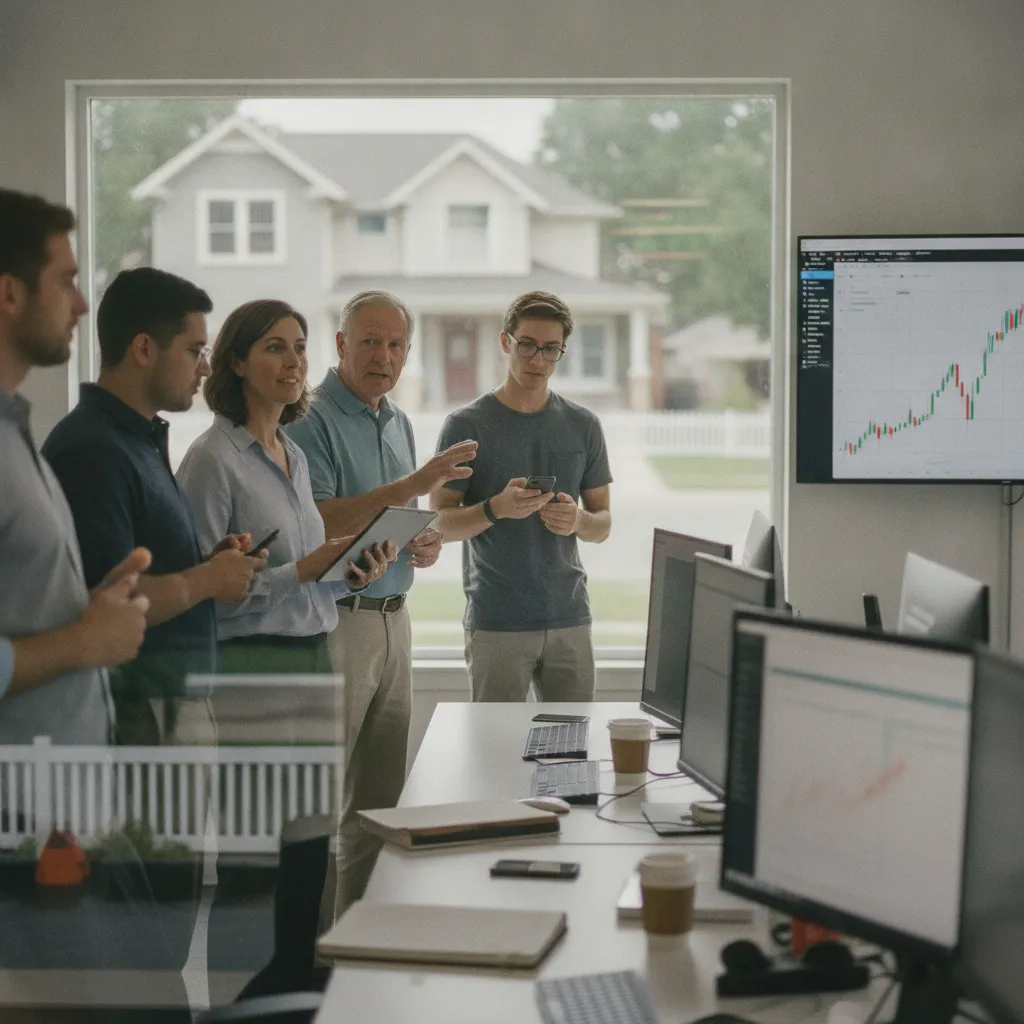
For decades, the quintessential image of the American Dream was rooted in land, defined by a white picket fence and a two car garage. However, recent Federal Reserve data suggests a historic pivot in how Americans build their fortunes. For the first time since World War II, U.S. households now hold more of their wealth in stocks than in real estate. Nearly half of all financial assets were held in equities during the quarter ending in June, marking a staggering climb from the lows seen back in 1982 and leaving real estate lingering around the twenty percent mark.
Financial experts point to a combination of explosive market growth and crushing housing costs as the primary drivers behind this shift. While inflation adjusted home prices have remained relatively stagnant, the S&P 500 has delivered consistent double digit returns over several years, making brokerage accounts far more attractive engines for wealth creation than property appreciation. This trend is particularly evident among Gen X and Millennials, many of whom face a prohibitively expensive housing market. With the average age of first time homebuyers hitting an all time high of forty, younger generations are increasingly turning to productive corporate assets rather than mortgages to secure their futures.
This evolution isn’t just about math; it’s about lifestyle and mobility. There has been a notable rise in millionaire renter households, suggesting that affluent Americans may now prioritize flexibility over permanent roots. While traditionalists argue that a home provides irreplaceable emotional value and unique leverage through down payments, advisors warn against tying too much capital into illiquid assets. In an era of economic volatility, having access to liquid wealth allows families to weather storms that those locked into overpriced homes cannot.
Ultimately, while the tools used to achieve security have changed, the underlying goal remains the same. Whether it is found in a deed or a digital portfolio, the pursuit of financial stability continues to drive American behavior. As housing becomes less accessible along coastal hubs and urban centers, investing early in equity markets has become less of a choice and more of a necessity for those hoping to maintain the standard of living their parents enjoyed through homeownership.